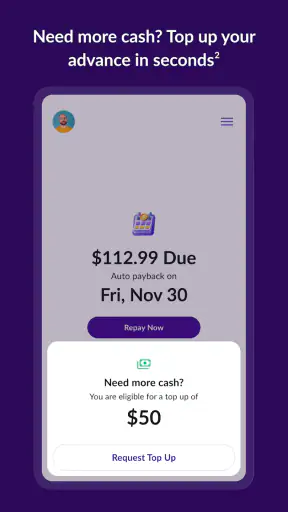
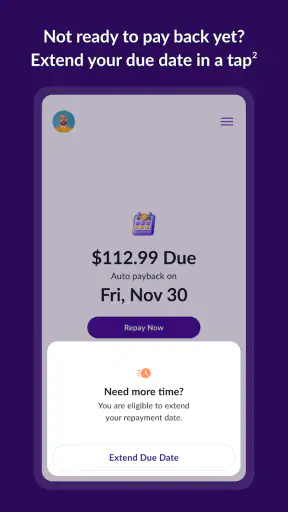
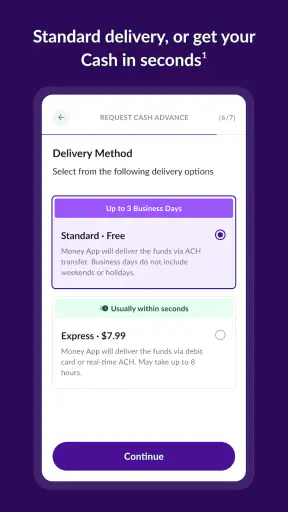
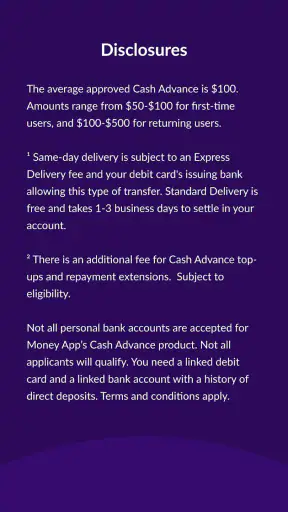
I approached Money App - Cash Advance as a practical finance tool rather than a general budgeting app. Its purpose is straightforward: help people look for emergency cash when an unexpected expense arrives before payday. That narrow focus is both its main appeal and the first thing to understand. It is not the kind of app I would open to plan a full household budget, compare every borrowing option, or replace a bank account. I see it as a short-term financial option that deserves careful attention before anyone relies on it.
The app is free to install, is aimed at Everyone, and comes from PRG Ventures. It has built a fairly visible user base, with more than half a million installs, a 4.2 average rating, and about ten thousand ratings overall. Those figures suggest that many people find the basic idea useful, but they should not be mistaken for a guarantee that every request will work the same way. Cash-advance services depend heavily on personal circumstances, eligibility, timing, and the information a user provides.
How Money App - Cash Advance fits into everyday finances
The most sensible way to use this app is for a defined, temporary cash gap. Imagine a necessary bill arriving a few days before your salary, or a small household expense appearing when your balance is already committed. In that situation, I would use the app to review whether an advance is available, examine the conditions carefully, and decide whether the short-term relief is worth the repayment obligation.
That last step matters more than the request itself. Emergency cash can solve a timing problem, but it does not remove the expense. Before proceeding, I would write down the amount needed, the date income is expected, and the payments already scheduled for that period. If repayment would leave me short again, the app would not be solving the real problem; it would be moving it forward.
Compared with a traditional bank overdraft, a credit card, or a personal loan, the attraction here is convenience and a more focused emergency-cash experience. A bank may offer stronger long-term financial tools, while a credit card can be more flexible for users who already have available credit. A personal loan may make more sense for a larger planned expense. Money App - Cash Advance is better suited to someone who wants to explore a smaller, immediate option without treating the situation as a long-term borrowing plan.
I would also avoid assuming that the word “advance” means guaranteed money. A request is not the same as approval, and approval is not the same as money arriving instantly. Timing can matter when an expense is due today, so I would not wait until the final minute to investigate the available option. The app is most useful when it gives me enough time to review the result calmly rather than forcing a rushed decision.
What the current version tells me about the product
The current release is version 2.47.0, and the app supports Android 7.0 or newer. That broad device compatibility is helpful for people who do not own a recent phone, especially when an emergency-money tool needs to be available on an older device. At the same time, compatibility alone does not tell me how smoothly the app will behave on every handset, so I would keep the operating system updated where possible and use a stable connection during important steps.
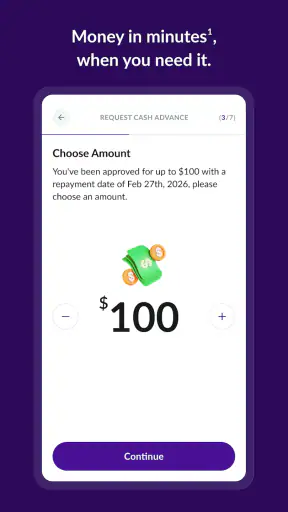
Because this is a finance app, I pay more attention to clarity than visual novelty. The useful experience is not about decorative screens; it is about seeing what I am requesting, understanding what I may need to repay, and knowing what happens next. A clean sequence is valuable here because confusion can turn a small cash shortage into a larger mistake.
One practical habit I recommend is taking a moment to read each confirmation screen instead of tapping through it automatically. I would check the requested amount, any repayment information shown, and whether the action is a request, an eligibility check, or a final acceptance. This is a simple workflow improvement, but it is especially important in an app built around urgent decisions.
What appears to have evolved
The release history represented by the current version shows that PRG Ventures continues to maintain the product rather than leaving it as a one-time experiment. That is encouraging for existing users because finance apps need ongoing attention as devices, account connections, and security expectations change. Still, a newer version should not be interpreted as proof that every personal experience has improved equally.
For me, the meaningful measure of product evolution is whether the app makes the borrowing journey easier to understand. Updates are most valuable when they reduce unnecessary friction, make status information clearer, and help users distinguish between an application step and an actual cash outcome. Those are the areas I would watch when moving from an older installation to version 2.47.0.
I would update before starting a new request, particularly if the installed copy is old. Keeping the app current can reduce avoidable compatibility problems, but I would still review the screens as a new user would. An update does not remove the need to check repayment details or confirm that the request fits my budget.
How existing users may feel the difference
Someone who has used the app before will probably value continuity more than extra features. When money is tight, I do not want to relearn a complicated process every time. A familiar route from opening the app to reviewing an available advance can make the experience less stressful. The current version should therefore be judged by how predictable that journey feels, not simply by its version number.
Existing users should also revisit their own habits. If I previously treated the app as a quick way to cover any shortfall, I would now use a stricter rule: only request an amount tied to a specific expense, and only when the next repayment can fit alongside ordinary bills. This approach protects against a common trap in short-term finance tools, where convenience encourages repeated use without a clear plan.
Another useful practice is keeping personal records outside the app. I would note the request date, amount, expected repayment timing, and the expense it covered. That gives me a simple history for deciding whether the service is helping with rare emergencies or becoming part of a recurring cycle. The app may make the request process easier, but a separate record helps me judge the broader financial effect.
Users changing phones or reinstalling should be prepared to verify their information again if requested. I would not rely on memory for account details, and I would avoid entering financial information while connected to an untrusted public network. These are not exciting tips, but finance apps deserve the same caution as online banking, especially when they are used during stressful moments.
Where the app is genuinely useful
Its strongest use case is a short-lived mismatch between income and an unavoidable expense. A person may have regular income but face a badly timed bill. In that case, the app can be worth considering because it focuses on emergency cash rather than asking the user to manage an entire financial system.
It may also suit someone who wants to review an alternative before using a credit card. Credit can feel convenient because it is already available, but that convenience can hide the longer repayment period and the possibility of carrying a balance. Exploring a cash-advance option may help a user compare the immediate choice with an existing credit facility instead of automatically reaching for the card.
However, I would not recommend making this the first choice for a continuing income problem. If rent, utilities, food, or transport costs are regularly higher than income, another advance is unlikely to fix the underlying gap. A conversation with a bank, employer, debt adviser, or trusted support service would be more appropriate. The app can be a temporary tool, not a substitute for broader financial help.
I would also skip it for a large purchase that can wait. If the expense is optional, waiting and saving is usually cleaner than borrowing. For a planned renovation, holiday, or major device purchase, a conventional savings plan or a carefully compared loan may offer a more suitable structure. The narrower the emergency, the easier it is to decide whether a short-term advance is appropriate.
The trade-offs that are easy to overlook
The first trade-off is speed versus reflection. A dedicated cash app can feel faster than contacting a bank, but speed increases the risk of accepting an option without understanding the full consequence. My advice is to treat every screen as a financial decision, not merely a technical step. If the terms are unclear, I would pause rather than assume the most favorable interpretation.
The second is simplicity versus financial depth. Money App - Cash Advance is easier to understand as an emergency-cash tool than as a complete money-management platform. That simplicity may be welcome when I need one focused task, but it also means I should not expect the kind of long-term planning, spending analysis, or broader account management I might find in a dedicated budgeting app or banking app.
The third is access versus repetition. Having a convenient place to explore an advance can be reassuring, yet that reassurance can encourage repeated borrowing. I would set a personal limit before opening the app: one specific emergency, one clear repayment plan, and no request merely to maintain discretionary spending. This boundary turns the app into a backup rather than a routine extension of income.
A fourth insight is that the best time to examine the app is before the emergency becomes urgent. I would install it, understand the general flow, and make sure I know where repayment information appears while I am calm. That does not mean requesting money in advance; it means reducing the chance of making a rushed choice when a bill is already overdue.
Questions I would answer before using it
Is it free to download? Yes, the app is listed as free. That describes access to the application, not the total cost or obligation connected with any cash advance. I would still inspect every amount and condition presented during the process rather than assuming that a free app means borrowing is free.
Can anyone use it? The content rating is Everyone, and the minimum supported Android version is 7.0, but that is not the same as saying every adult will qualify for an advance. I would treat the age and device information as access guidance, while viewing eligibility as a separate matter determined during the app’s own process.
Is it a replacement for a bank? I do not see it that way. A bank remains more appropriate for regular deposits, broader account services, established credit products, and long-term financial management. This app makes more sense as one possible emergency-cash route alongside those services.
What should I do if I need money immediately? I would first confirm the exact amount needed, check whether the expense can be delayed, and review the repayment impact on the next pay cycle. Then I would use the app early enough to understand the outcome. If the timing or terms do not work, I would compare a bank option, an existing credit facility, or direct help from the bill provider rather than repeatedly submitting requests.
How can I tell whether it is helping me? After using it, I would look beyond whether the immediate bill was covered. I would ask whether repayment was comfortable, whether I had to borrow again, and whether the emergency was genuinely unusual. If the answer shows a repeating pattern, the right next step is financial planning or advice, not deeper dependence on the app.
What I would like users to watch going forward
For future updates, I would watch for clearer explanations around request status, repayment timing, and the difference between a preliminary step and a completed advance. Those details matter more to me than cosmetic changes. A finance app earns trust when it helps users understand what has happened and what will happen next.
I would also pay attention to how smoothly the current version works on older supported devices. Supporting Android 7.0 or newer gives the app a broad reach, but real usefulness depends on dependable performance during account verification and urgent requests. Users with older phones should update the operating system where possible and avoid postponing setup until a bill is already due.
The size of the user community gives the app some visibility, while the 4.2 average suggests a generally positive reception with room for individual differences. I would read recent user feedback with a practical filter: look for comments about clarity, timing, reliability, and repayment understanding rather than focusing only on praise or complaints. A finance product can work well for one person and be unsuitable for another because their income pattern and emergency are different.
My final view is cautiously positive. I like the focused purpose, the free entry point, the broad Android support, and the fact that PRG Ventures is maintaining the app through version 2.47.0. I would recommend it to someone facing a genuine, short-term cash timing problem who is willing to read carefully and plan repayment before requesting anything.
I would not recommend using it casually, for optional purchases, or as a solution to recurring financial pressure. Its value depends less on how quickly I can open the app and more on whether the advance fits a realistic plan. Used with that discipline, Money App - Cash Advance can be a useful emergency option; used without it, the convenience may simply postpone the same problem.


